
On Tuesday afternoon the Reserve Bank hands down its rate decision, and 30 minutes later 24 horses jump in the race that stops a nation.
Point Of Law is the favourite at $6, while the market has the chances of the RBA raising to 4.85% at 95% (about $1.05 on the tote).
No on-course bookie will give you odds that short on anything with four legs, making the RBA Tuesday’s shortest-priced favourite. To be expected after September inflation came in at 4.3% on Wednesday.
Either way, we’ll have the RBA on one screen and Flemington on the other. A rate rise makes every raise at the small end harder, and this week we counted close to 200 juniors who need one before Easter.
Away from the rates, our copper pick turned up in our own portfolio, and Elk’s first hole came back better than we hoped.
What caught our eye this week:
- Delegations from Canada to Peru fill IMARC, all hunting the same dollars
- Bubalus becomes our copper pick 10km from Mt Lyell
- China pays its biggest copper premium since 2017
- Elk’s first hole runs 290 metres of gold
- We read 700 quarterlies and found 16 companies worth less than their cash position
- Twelve small-cap funds shut and the Small Ords bounces anyway
- Mount Ridley gets flown to Ankara to present Selectro
- A 7c explorer nearly doubles on Namibian gold ground
- DXN loses its first AI customer and Rumble’s study sinks the stock
Let’s get to it.
IMARC 2026: A Quieter Floor in Sydney
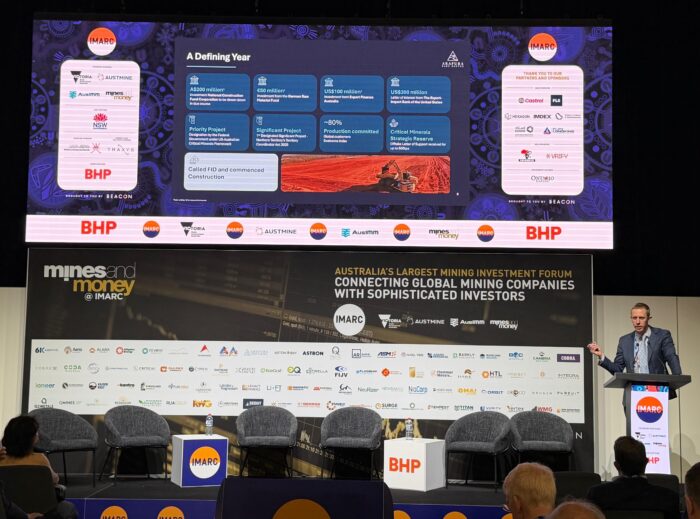
We spent a couple of days on the floor at IMARC in Sydney this week, and we have to admit it felt quieter than the past couple of years.
IMARC is the biggest mining conference in the country. It takes over the convention centre at Darling Harbour for three days, with about 12,000 people through the doors and 500 exhibitors.
Flags filled the floor this year. Canada had a pavilion, so did Germany, France, Sweden and Peru, and every Australian state sent a delegation with a minister or a trade commissioner telling anyone who stopped why their ground is the place to dig.
They’re all chasing the same money. There’s only so much exploration capital in the world in a year, and the countries are now bidding against each other for it.
Last year the talk on the floor was critical minerals. They were still around this year, but every broker and fund manager we sat down with was hunting the same type of company, a copper project with a path to development.
About 70 small-cap explorers paid for stands and turned up anyway. Every one of them knows the market is tough, and most of the conversations were about spending carefully and keeping the project moving until money flows back.
Plenty of them are pushing a resource forward. Plenty more are in a state of flux, trying to get attention for a project the market has fallen out of love with, and we felt for them.
Agnico Eagle’s Australian boss Ion Hann was on the speaker list, and the room was full before we got to the door. Agnico paid US$14.8 million a fortnight ago for a slice of the ground around Elk Range Mining’s Friday mine in Idaho, and we wanted to hear what it sees in the district.
We came home with a shorter list of companies than last year and a longer list of countries. We’d been looking for the same copper company as everyone else on the floor for months, and on Tuesday we found it…
Bubalus Resources (ASX: BUS) is Our Small-Cap Copper Pick
It was sitting in our own portfolio.
On Monday Bubalus Resources (ASX: BUS) announced a binding deal to buy Skyline, a copper-gold project in western Tasmania 10km from Mt Lyell.
Mt Lyell produced 1.4 million tonnes of copper over a century and then sat idle for 12 years. Sibanye-Stillwater is now spending $490 million to restart it, with first copper due in 2029.
Copper is sitting near the record it set in September, and the big miners are going back over old ground like Mt Lyell because the new discoveries have dried up.
We’ve owned BUS since 2025, through a gold drilling program at Avon Plains in Victoria that came back lighter than any of us wanted. Managing director Brendan Borg spent this year looking for a better project, and our full write-up on what he found is here.
Skyline spent the past year inside a Toronto-listed company that ran short of money to drill it. Borg told us what it needed was a well-funded explorer to work out how big the copper system is.
The lead prospect is Jukes, where 13 holes have gone in and every one of them hit copper. The best metre ran 6.28% copper and 12.2 grams of gold, and the copper runs from near surface to about 430 metres down.
Five kilometres south at Hydes the copper sticks out of the ground and nobody has drilled under it yet. Behind the two of them sits 80km of strike along the volcanics Mt Lyell was built on.
Borg says the copper at Jukes looks a lot like Mt Lyell’s, and the communities around Queenstown are well used to mining and want more of it.
Nick Jolly joined the board with the deal. He ran the geology at Spartan Resources while it found 2.37 million ounces and sold to Ramelius for $2.4 billion, and he’s putting his own money into the raise alongside Borg and the rest of the board.
The drilling permits for Jukes and Hydes are already in place, so once the deal closes in December the only job left is getting a rig and a crew to site. Borg expects to start at Jukes in January and move to Hydes, and he may put a rig on each and run them at the same time.
He told us a five or 10 metre hit at 3 or 4% copper is where the project starts to sing. After a quiet year holding BUS, January can’t come quick enough.
China Pays Up for Copper as Oyu Tolgoi Pauses
Trucks loaded with copper from Rio Tinto’s Oyu Tolgoi mine in Mongolia spent the week queued at the Ganqimaodu border crossing into China.
On the Chinese side of the border, importers paid US$205 a tonne above the going London price just to get copper delivered to their ports, up from US$145 a week earlier and the biggest premium since 2017.
Part of the rush is Trump. Traders spent this year shipping copper into America before he widens his tariffs to refined metal, and it’s sitting in US warehouses.
China’s stocks are below normal and its smelters have cut output, and one Chinese analyst summed the market up in three words this week: “Sold out everywhere.”
Then on Thursday night Rio paused the Oyu Tolgoi underground after a tremor on a fault zone hurt three workers. Once the underground is at full tilt it will be one of the biggest copper mines in the world.
Grasberg in Indonesia is the second-biggest copper mine on earth. Its owner Freeport has it running at about two-thirds of its old rate since last year’s mud rush, with full speed due late in 2027.
Those two mines were meant to carry a fair share of the world’s new copper this decade, and a new mine to make up what they’re missing takes 10 to 15 years to permit and build.
BHP’s finance boss sees a lasting shortfall from about 2028 and says the world needs another eight to 10 million tonnes a year by the mid-2030s. It’s more than a third of what every mine on earth digs up today.
Bank forecasts come and go, and we’ve learnt to watch the warehouses more closely than the spreadsheets. For once both point the same way.
The next discoveries come from juniors, and ours turns a rig at Jukes in January.
Elk Range Mining (ASX: ELK) Hits 290 Metres of Gold in First Hole
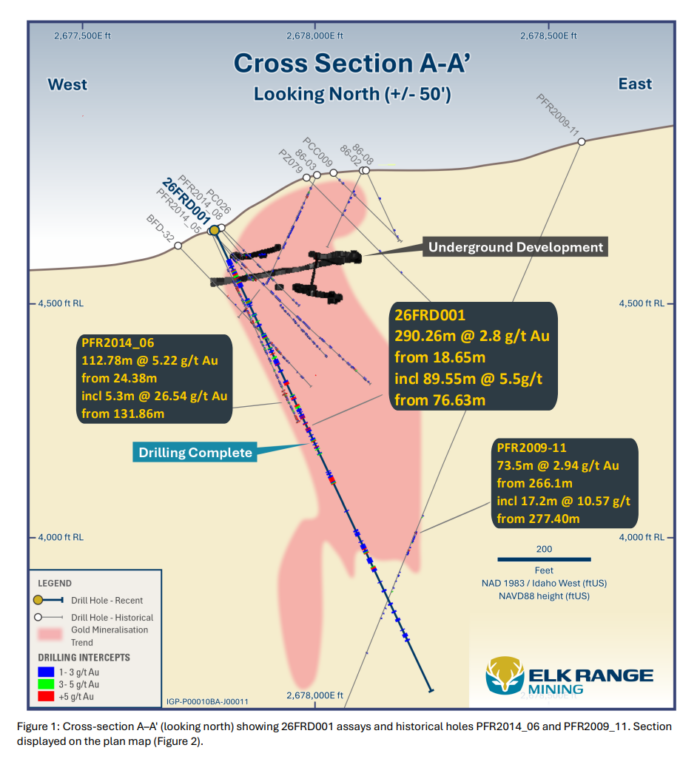
The lab result we waited 11 weeks on landed on Tuesday morning, and our Idaho gold explorer Elk Range Mining (ASX: ELK) came out of its halt with 290 metres of gold at 2.8 grams a tonne from 19 metres down.
Plenty of mines make good money on a couple of grams a tonne, and the best 89.6 metres of this hole ran 5.5 grams.
Elk drilled this one down the length of the structure, so the gold is thinner than the metres suggest, and the next seven holes cut across it to measure the thickness a mine gets built on.
Friday is a built and permitted underground gold mine in central Idaho the last owner parked during Covid. The best hole anyone drilled there ran 112 metres at 5.22 grams in 2014 and stopped at 137 metres with gold still in the core.
Elk put its first hole eight metres from it and kept going. The richest stretch starts at 137 metres, right where the old crew pulled their rods, and runs 11.3 metres at 21.4 grams. The gold kept coming to 309 metres.
CEO Edward Keys told us three of the five spots where the crew photographed gold in the core stayed on Elk’s half when the saw went through, so those trays are off to conferences as show pieces.
Around 386 holes have been drilled at Friday over the past century and all of them were reported under an overseas code, so on the ASX they don’t count until Elk’s own core backs them up. This hole is the first to do it.
The shares ran to 24.5c on Tuesday morning, 80% above the halt price, and the sellers spent the rest of the week pushing them back to 14.5c. We haven’t sold a share.
We think the selling is short-sighted. At 14.5c Elk is worth about $18 million, and $6.7 million of it is cash in the bank. The rest buys a built mine with this hole’s gold in it, and the second and third holes are already at the lab with assays due in late November.
We Read 700 ASX Quarterlies so You Don’t Have to
Every explorer and early-stage company on the ASX has to lodge a cash report within a month of each quarter ending.
The report says how much cash the company had on September 30 and how many quarters of money it has left at its current rate of spending.
We ran a scan through every one lodged this month by a company worth less than $50 million, and there were close to 700 of them.
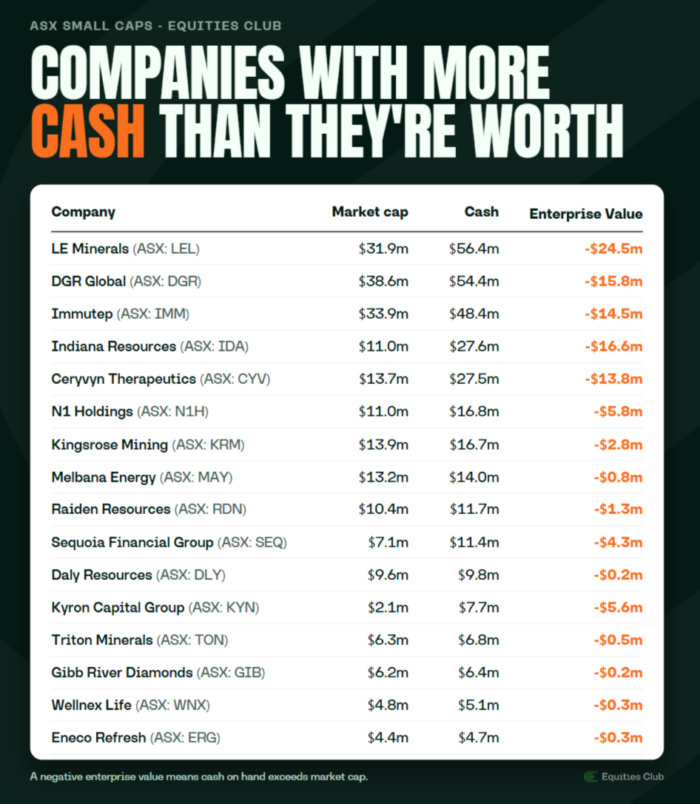
Sixteen of them hold more cash in the bank than the whole company is worth on the ASX, and another dozen trade within 20% of their cash. Buy one of the 16 and the business comes for nothing.
We’ve listed them all, thank us later.
At the other end, three in 10 finished September with less than $1 million in the bank, and half the lot have less than $2 million.
The quarterly report also asks each company how long its money lasts at the rate it’s spending. A third said less than six months, and one in six said less than three.
That’s a bit frightening as roughly 200 companies at the small end have to pass the hat before Easter, into a market where trading is thin and a rate rise is due on Tuesday.
The ones with a decent story will get a placement away at a discount, and the ones who can’t usually go looking for a project to vend in or a cashed-up shell to merge with.
A quarter like this one is when those deals get done, and if you’re one of the 16 sitting on more cash than your company is worth, expect the phone to start ringing.
Twelve Small-Cap Funds Shut, Small-Caps Bounce Anyway
The AFR counted at least 12 small-cap funds closing their doors in 2026, up from eight last year, and the index they’re all measured against has fallen 16% this year.
What a fund manager calls a small-cap and what we call a small-cap are two different animals.
The index is the Small Ords. It takes the 300 biggest companies on the ASX, drops the top 100 and tracks the 200 left over, so it runs from companies worth a few hundred million dollars up to a couple of billion.
The companies we back are worth $10 million or $20 million, and when the Small Ords falls the money leaves the whole small end of the market. An explorer our size feels it long before anything in the index does.
A fund shuts when its clients pull their money out. To pay them back it has to sell every share it owns, and 12 funds doing it in a year is a lot of small-cap shares going out the door at once.
Then in the same week the AFR ran the funeral notices, the Small Ords climbed about 3% off its 52-week low.
When every man and his dog is punting small-caps you’re close to the top, and when the funds are packing up and sentiment is in the bin you’re a lot closer to the bottom than you realise.
We’ve seen a few of these cycles, and the funds shut near the bottom in every one of them.
Mount Ridley Mines (ASX: MRD) Heads to Ankara
The critical minerals explorer in our portfolio Mount Ridley Mines (ASX: MRD) rose 6.7% this week on an invitation.
On Thursday, managing director Allister Caird was asked to present at the International Mineral Exploration Conference in Ankara, Turkey, next week.
MRD built its Selectro leach for the scandium clay at its Grass Patch project near Esperance, and this month it pulled 95% of the gallium out of WA bauxite with the same chemistry.
China refines nearly all the world’s gallium and the chips in American radar run on it, which is why three governments are paying for a gallium plant at Alcoa’s refinery south of Perth.
Caird will put Grass Patch and Selectro in front of a room of miners and technology companies from around the world, and the organisers are paying for the flights and the hotel. They must see something they like.
We’ll catch up with Caird when he’s back.
NGX Limited (ASX: NGX) Nearly Doubles on Namibian Gold
It’s not all doom and gloom out there, because the biggest small-cap gainer of the week went from 7c to 13c, up 86%.
A Perth explorer called NGX Limited (ASX: NGX) holds rutile and graphite ground in Malawi, and on Tuesday it bought its way into Namibia’s Damara Belt.
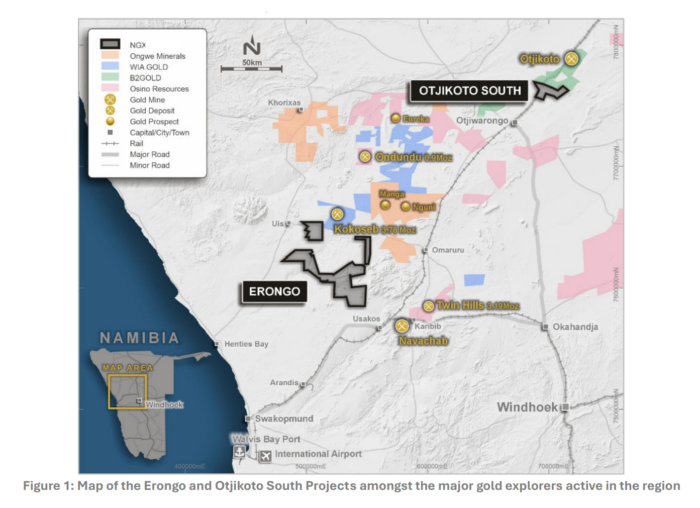
The Damara Belt is a band of gold-bearing country running across central Namibia.
WIA Gold found its 3.78 million ounce Kokoseb deposit there, and Canadian miner B2Gold digs gold from its Otjikoto mine on the same belt.
NGX can earn up to 85% of seven licences covering more than 1,300 square kilometres along the belt. One sits within 10km of Kokoseb, and another is ground B2Gold handed back next to Otjikoto.
It got in for small change, with US$545,000 in cash for the first 51% and the rest paid in stages over seven years as the work gets done. NGX raised $3.6 million on the back of it, and the directors put $540,000 of their own money in.
Nobody has drilled a hole on the new ground yet. NGX starts with soil sampling along the faults the belt’s gold sits on, and at 13c the whole company is worth about $11 million.
Buyers paid up for 1,300 square kilometres next to a 3.78 million ounce discovery, and NGX got in for under $1 million up front.
There are still winners out there.
DXN (ASX: DXN) and Rumble Resources (ASX: RTR) Have a Brutal Week
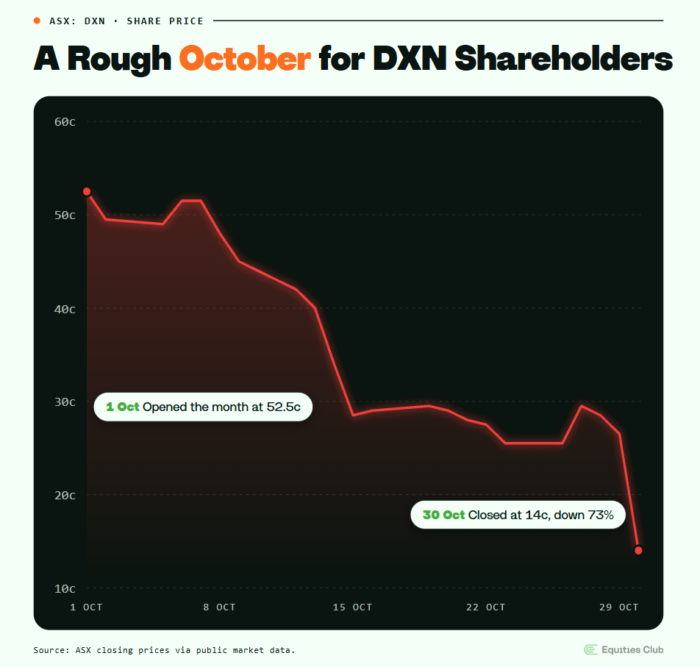
DXN (ASX: DXN) builds data centres in modules at a factory in Welshpool. In June it signed an $8.8 million contract to build an AI data centre for a US-listed cloud company, and we wrote about it when the shares ran 775% in a week.
On Friday DXN said the customer intends to cancel the contract after a change of strategy.
DXN expects to be paid about $4.2 million for the work it has done and the parts it has ordered, but the bigger campus the contract was meant to lead to looks unlikely.
The shares fell from 26.5c to 14c on Friday.
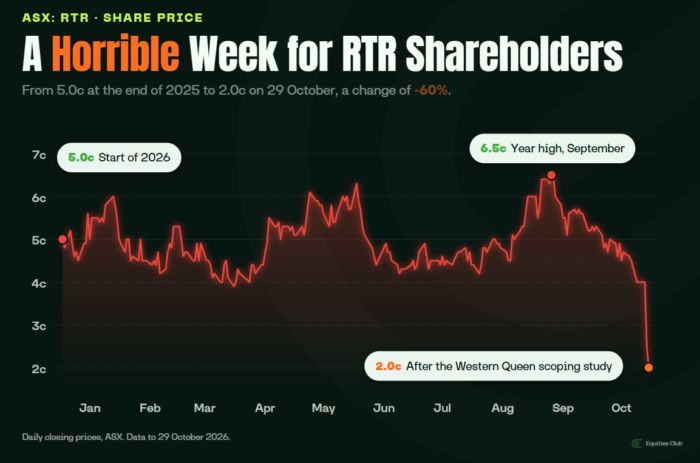
Rumble Resources (ASX: RTR) owns the Western Queen gold project in WA, and on Tuesday night it put out the study it had told the market all year would lead to a mine decision before Christmas.
Rumble plans to dig about 125,000 ounces over four years and truck every tonne 185km to another company’s mill, at a cost of A$4,390 an ounce. The study assumes gold at A$5,714, so each ounce clears about A$1,300 before tax.
Rumble has been hitting high-grade tungsten alongside the gold at Western Queen all year, and the study leaves it out, so the feasibility work has to be redone to fit the tungsten in. The mine decision has no date on it and the money to build the mine is still to be found.
By Wednesday’s close the shares were down 37.5%, from a company worth $53 million at the start of the week.
Holders waited a year for a date and got another study.
The Week Ahead on the ASX
We’ll put down the pens for a pint straight after the RBA’s 2.30 decision on Tuesday and watch the race with the rest of the country.
Tuesday is also midterm election day in America, and the Republicans are long odds to hold either house. A double loss would tie Trump’s hands on the AI and resources push Wall Street has been running on, and Bank of America thinks US stocks could fall more than 10% on it.
We remain busy. We’ve met plenty of boards in the past few weeks who want to be in front of investors when the market turns, which tells us they can see the light, and our job is to work out which of them we’d back.
Good luck on Tuesday. We hope you back a winner at longer odds than the Reserve Bank.
Till next week.
General advice, disclosure and confidentiality
General advice warning
The contents of this document are intended to provide general securities advice only and have been prepared without taking account of your objectives, financial situation or needs. Because of that you should, before taking any action to acquire or deal in, or follow a recommendation (if any) in respect of any of the financial products or information mentioned in this document, consult your own investment advisor to consider whether that is appropriate having regard to your own objectives, financial situation and needs. If applicable, you should obtain the Product Disclosure Statement relating to the relevant financial product mentioned in this document (which contains full details of the terms and conditions of the relevant financial product) and consider it before making any decision about whether to acquire the financial product. Whilst Equities Club Pty Ltd (”Equities Club”) believes information contained in this document is based on information which is believed to be reliable, its accuracy and completeness are not guaranteed and no warranty of accuracy or reliability is given or implied and no responsibility for any loss or damage arising in any way for any representation, act or omission is accepted by Equities Club or any officer, agent or employee of Equities Club or any related company.
Neither Equities Club, nor any of its directors, authorised representatives, employees, or agents, makes any representation or warranty as to the reliability, accuracy, or completeness, of this document or any advice. Nor do they accept any liability or responsibility arising in any way (including negligence) for errors in, or omissions from, this document or advice.
Disclosure
The directors, authorised representatives, employees and associated persons of Equities Club may have an interest in the financial products discussed in this document and they may earn brokerage, commissions, fees and advantages, pecuniary or otherwise, in connection with the making of a recommendation or dealing by a client in such financial products. Equities Club owns 625,000 ELK shares, 2,083,333 MRD performance rights and 303,030 MRD shares, and 600,000 BUS shares at the time of publishing this article. Equities Club has been engaged by BUS, MRD, and ELK at the time of writing.
Confidentiality notice
The information contained in and accompanying this communication is strictly confidential and intended solely for the use of the intended recipient/s. The copyright in this communication belongs to Equities Club. If you are not the intended recipient of this communication please delete and destroy all copies immediately.
Equities Club Ltd (CAR No. 001308139) is a corporate authorised representative of ShareX Pty Ltd, Australian Financial Services Licence (AFSL) No 519872.