
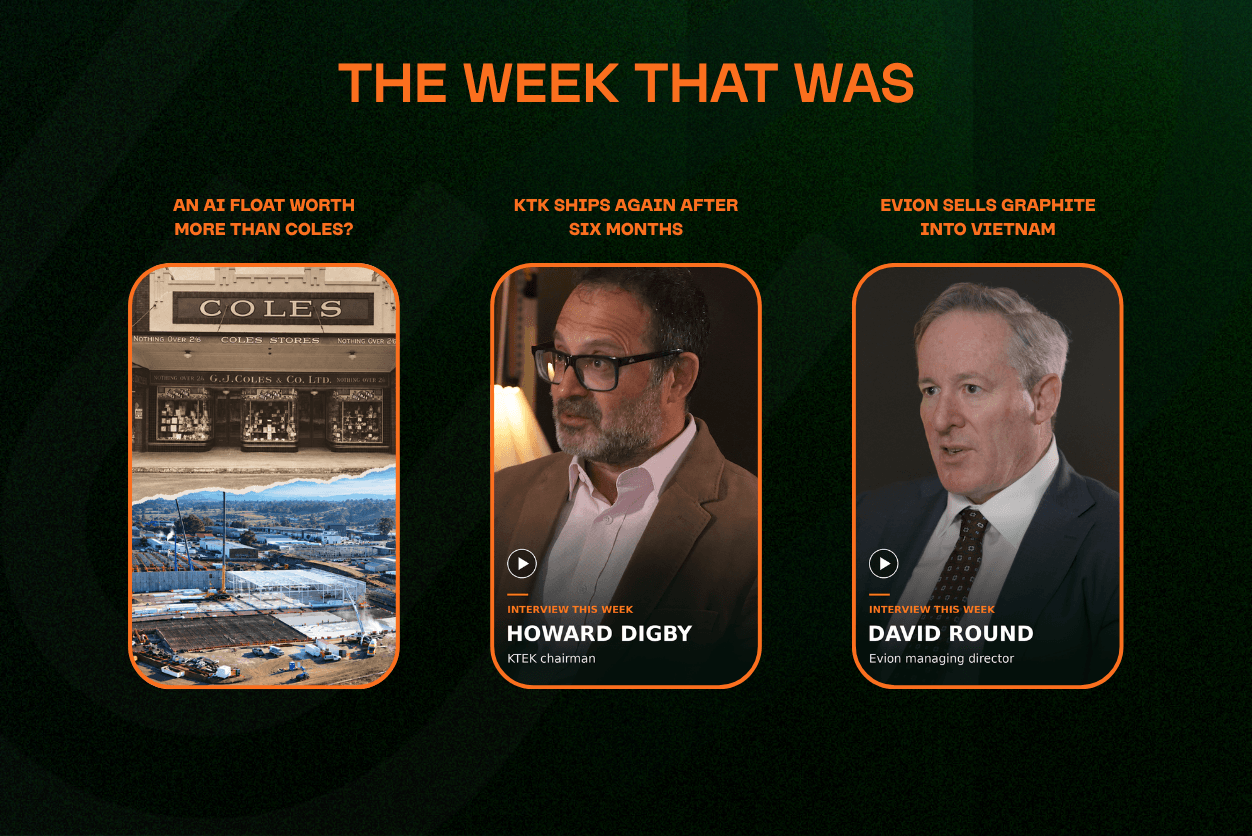
George Coles opened his first shop in Melbourne in 1914 and promised nothing in it would cost more than a shilling. The big drawcard on opening day was a mixing bowl.
His company now has more than 800 shops and sells things for much more than a shilling (about 10 cents). Coles collected $45.6 billion through the tills last FY and on Friday was valued around $30.6 billion.
112 years later, Firmus is the upcoming float every fund manager and newspaper in the country is talking about. It started life as a bitcoin miner.
These days it owns data centres full of the computer chips to run AI, and has contracts to rent them to the owner of Facebook and the maker of ChatGPT. It has two running and five more on the way.
The fundies start bidding on Tuesday, and the $11 a share they’ve been asked to pay makes Firmus worth $43.7 billion.
Firmus expects to lose US$77 million in the first half of this financial year. Coles made $1.09 billion.
One fund manager told the AFR Firmus was the “BHP of the token generation” (we sat with that one for a moment). Another said he’d short it.
Either could be right, and at that price we’d be on the short side. Then again, in 1914 we probably wouldn’t have backed the bloke selling mixing bowls.
Firmus is too big for us to touch either way. In our neck of the woods the drone company we’re bullish on started shipping again and one copper hole added $20 million to an explorer’s value.
This also caught our eye:
- KTK begins shipping again as demand continues to build
- Lynas bids for a rare earths stock that traded at 1c in 2022
- EVG sells its first container of graphite into Vietnam
- Paradigm calls in the administrators six days after its trial failed
- 10X finishes drilling at Balerion and heads to Black Hammer
- Boa hits 22m at 3% copper and adds $20 million in value
- Mamba and Micro-X run again a week after we wrote them up
- Northern Star knocks back a $38.7 billion offer from Gold Fields
- Liontown commits $389 million to expanding Kathleen Valley
Let’s get to it.
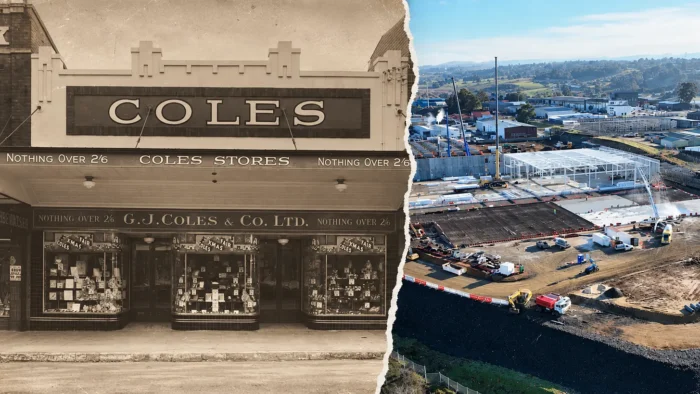
Same same, but different?
KTEK Aerosystems (ASX: KTK) Restarts Drone Airframe Deliveries
We heard the sobering stat this week that a Russian soldier’s life expectancy once they reach the frontline of the Ukraine war is about 20 to 30 minutes.
It came from Torsten Reil, co-founder of European drone maker Helsing, who said drones have made the front so deadly tanks are basically useless and he expects armies to stop sending people onto the battlefield at all.
He argued 100,000 strike drones on a country’s border could stop any land war, and it’s no doubt the thinking that lies behind the Pentagon asking Congress for about US$75 billion for drones and counter-drone systems next year, and Australia committing up to $22 billion over the decade.
Our drone company KTEK Aerosystems (ASX: KTK) builds the wings and body sections for military drones, and on Wednesday it started shipping to its biggest customer again.
The Pentagon prefers American-made parts, and KTK now assembles its airframes in LA.
The Iran war shut KTK’s shipping route in March, and KTK took in just $273,000 from customers in the June quarter. The first batch is now ready for collection, so KTK can start invoicing again.
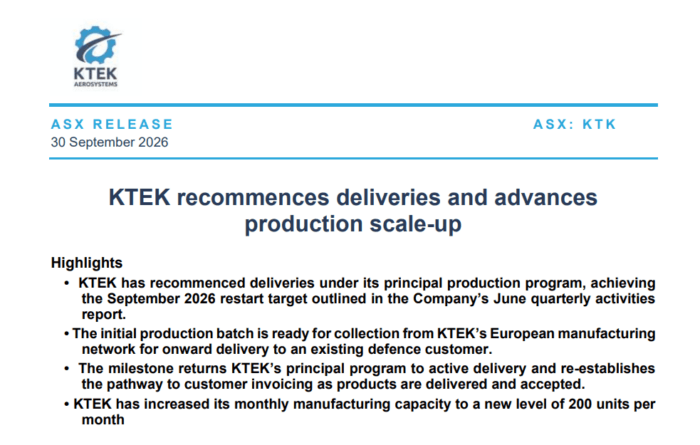
KTK’s partner factories built about 50 airframes a month last year. They can now build 200, which KTK puts at $1.66 million a month at last year’s prices.
One of Israel’s three big defence contractors placed its first order a fortnight ago. Founder Dekel Keisar ran drone structures at Israel Aerospace Industries before he started KTK, and he still owns 36% of it.
KTK closed the week at 17c, about $24 million. We paid 20c at the float in May and we’re bullish on the next 12 months.
We sat down with chairman Howard Digby last week. He’s also a director of drone communications company Elsight (ASX: ELS), which has gone from 45.5c in mid-2024 to $5.32 on Friday.
Digby told us he isn’t brave enough to pick the winning drone maker, so he backs the companies that sell to all of them.
The video is below.
Lynas Rare Earths (ASX: LYC) Bids $968 Million for Meteoric Resources (ASX: MEI)
A share that traded at 1c in mid-2022 got a takeover offer worth about 28.6c on Thursday.
Lynas Rare Earths (ASX: LYC) digs rare earths at Mt Weld in WA and processes them in Malaysia. It calls itself the only commercial producer of separated rare earths outside China. (Rare earths go into the magnets inside EV motors and missiles).
Meteoric Resources (ASX: MEI) owns Caldeira, a clay rare earths deposit in Brazil. It bought the rights in December 2022 for US$20 million from a family who had dug the clay for over 100 years to make bricks.
LYC wants MEI.
Lynas is paying in shares, 0.0207 of a Lynas share for every Meteoric share, so the offer rises and falls with the Lynas share price.
On Lynas’ price before the deal the offer came to 28.6c, a 68% premium, and valued Meteoric at about $968 million.
Lynas fell 8.6% on the day, and at Friday’s close of $12.95 the offer is worth 26.8c.
A punter who put $1,000 into Meteoric at 1c would be swapping it for about $26,800 of Lynas shares just four years later. Good business.
Lynas is also lending Meteoric up to $110 million. Meteoric got $35 million at signing, and the other $75 million only comes if the deal is still alive in six months.
Evion Group (ASX: EVG) Sells Its First Expandable Graphite Into Vietnam
David Round runs Evion Group (ASX: EVG), the graphite and fluorspar company in our portfolio, and a few weeks ago he was at a defence conference in Philadelphia where robots walked the floor and he got to play with the guns.
He told us every piece of kit in the room had expandable graphite in it somewhere.
Expandable graphite swells up when it gets hot and smothers a fire, which is why it goes into fireproofing for warships and armoured vehicles.
China produced 82% of the world’s natural graphite last year, and since December 2023 its exporters have needed a government licence to ship it.
EVG makes expandable graphite at a plant near Pune in India, through a 50:50 joint venture called Panthera.
This week Panthera sold its first container into South-East Asia. A buyer in Ho Chi Minh City ordered about 20 tonnes at US$3,650 a tonne.
Panthera sold to the US and Europe last financial year for between US$3,100 and US$3,400 a tonne, so Vietnam paid 7% more than its best price.
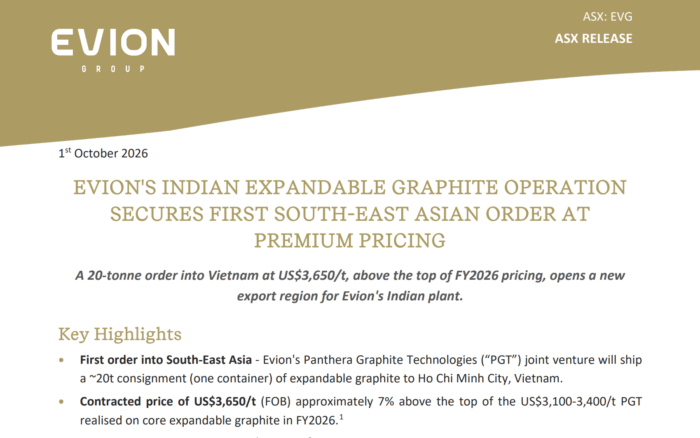
The container is worth about $104,000 across the joint venture and EVG owns half. It’s small money (we said the same about KTK’s first order), but these things have a tendency to grow quickly over time.
The plant sold 720 tonnes last year and is working towards 2,500 tonnes a year, so we’ll be watching for repeat orders. Managing director David Round says Panthera is negotiating ongoing supply with the same buyer and talking to buyers in Japan.
Round has also been in Washington with Arthur Sinodinos, the former Australian ambassador EVG signed as an adviser in June, and he told us Sinodinos got them in front of senior Pentagon people.
We like that a buyer in a new part of the world paid more than Panthera’s existing customers on its first order. We sat down with Round for a full breakdown of the next few months:
Paradigm Biopharma (ASX: PAR) Calls in Administrators After Failed Knee Trial
A Melbourne biotech worth about $140 million a fortnight ago called in administrators on Wednesday.
We wrote last week about Paradigm Biopharmaceuticals (ASX: PAR) and Zilosul, its injection for the pain of knee osteoarthritis. The drug’s big trial had 538 patients and was stopped at the halfway mark because the early results weren’t good enough to keep going.
A week later the board says Paradigm owes more in the short term than it can pay. FTI Consulting now runs the company and the directors’ powers are suspended.
Creditors meet on Friday. The board wants a deed of company arrangement, a deal where creditors agree to take less or wait longer so the company survives in some form.
Shareholders stand last in the queue behind the lender and every other creditor. The shares last traded at 24c, they stay suspended, and Paradigm expects the process to take at least eight weeks.
We said last week we like biotech, and a failed trial taking the whole company with it is the risk every holder signs up for.
Exultant Mining (ASX: 10X) Moves From Balerion to Black Hammer Copper-Gold
The last lab results from Balerion came back on Thursday for Exultant Mining (ASX: 10X), the NSW explorer in our portfolio.
Balerion is a silver and zinc prospect on 10X’s Peak View project near Cooma, and 10X drilled six holes there in August. Five of the six holes hit metal, and the best ran 11.75m at 9.12 grams a tonne of silver and 1.43% zinc and lead from 240m down.
The grades are modest and the zone gets thicker the deeper 10X drilled. The team did what it said it would do, but it’s time to park Balerion and move on.
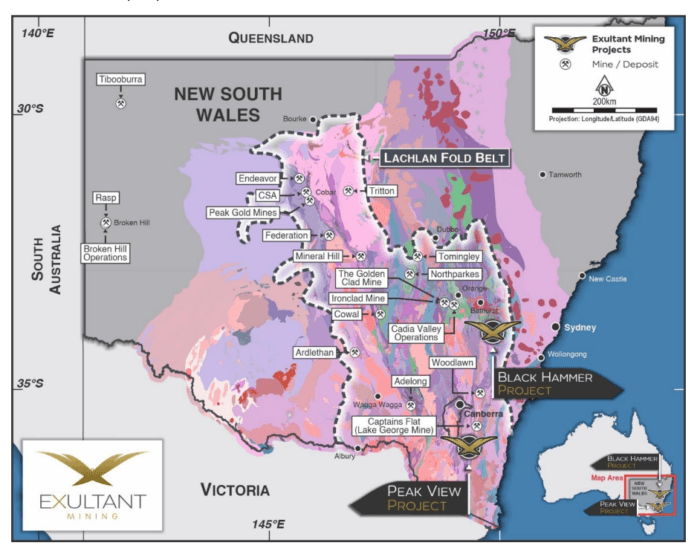
The crew has been at Black Hammer since early September. It’s 390 square kilometres of copper-gold ground in the same belt as Newmont’s Cadia, one of the biggest gold and copper mines in the world, and its three best targets have never been drilled.
10X closed at 13c, a valuation of about $5 million, with $3 million in the bank. We think it’s cheap, and a copper discovery at Black Hammer could move it a long way.
Boa Resources (ASX: BOA) Hits 22m at 3% Copper at Ricci Lee
Speaking of copper, a WA explorer drilled 22m at 3.05% copper this week and its shares went from 10.5c to 17.5c.
Boa Resources (ASX: BOA) hit it at Ricci Lee, a prospect on its Neds Creek project in the same district as Sandfire’s old DeGrussa copper mine.
The hole struck copper from 250m down, and 9m of it ran 6.86%. (Boa hasn’t worked out the true widths yet.) Plenty of the world’s big open pit copper mines dig rock grading under 1%.
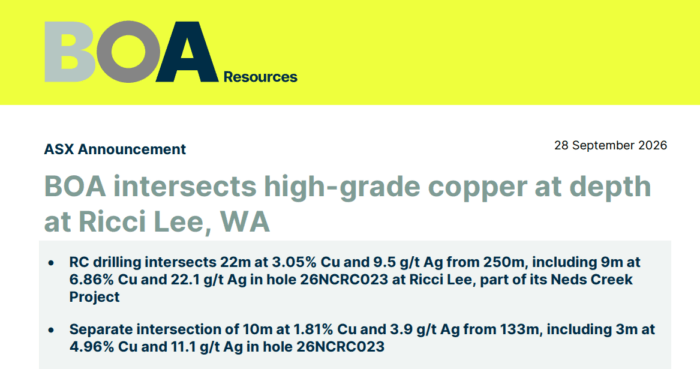
The same hole found a second copper zone higher up, 10m at 1.81% from 133m.
Boa has drilled 46 holes at Ricci Lee and the lab still has 36 of them, so more results land between now and Christmas.
Boa owns 49% of the ground today. Shareholders vote on October 12 on a deal to buy the other 51%, along with a couple of copper deposits next door.
Last Friday Boa was worth $30.5 million, and it finished this week at $50.9 million.
Buyers are still paying up for copper juniors with real hits, and we’re still hunting for one to add to our portfolio.
Mamba Exploration (ASX: M24) and Micro-X (ASX: MX1) Run Again
Peter Cook founded Westgold, a $5 billion gold miner with a mill at Meekatharra. On Friday he signed on as an adviser to a copper-gold explorer just down the road he already owned shares in.
The explorer is Mamba Exploration (ASX: M24). We wrote about it last Sunday at 3.6c, after it went back through old drilling and found 165 copper hits in 47 holes.
Mamba announced Cook and a $6 million raise at 3.8c on Friday morning, and by the close its shares were 7.1c.
Mamba will spend the money on 6,000m of drilling at Meeka East starting this month, with first results due in December.
Micro-X (ASX: MX1) was another we mentioned last Sunday. It had tripled to 4.5c in a week after its chairman bought shares on market.
It builds X-ray scanners light enough for an ambulance, and the US Department of Homeland Security is paying it to design an airport checkpoint where passengers screen themselves.
On Monday the department gave it another US$750,000 to build a better baggage scanner over the next eight months, and the stock closed the week at 6.2c.
A fortnight ago Mamba was 2.1c and Micro-X was 1.8c. The ground can move quick in this game.
Northern Star (ASX: NST) Rejects $38.7 Billion Gold Fields Takeover Offer
Now to the big boys, the week opened with the owner of Kalgoorlie’s Super Pit turning down a $38.7 billion takeover offer.
Northern Star Resources (ASX: NST) confirmed on Monday it had rejected South Africa’s Gold Fields, which offered 0.3125 of its own shares plus $7.25 cash for each Northern Star share.
Gold Fields’ shares have fallen since it made the offer, so the $27 a share it started at was down to $25.19 by Monday.
Chairman Michael Chaney called the offer highly opportunistic and said the price fell well short. He also said most of it would be paid in shares in Gold Fields, which has mines in riskier countries than Northern Star does.
Northern Star sold 1.54 million ounces of gold last financial year for an average of $4,925 each, and they cost $2,698 each to dig up.
Both companies have bought a junior with a discovery in the past 18 months. Northern Star paid $5 billion for De Grey, which found the Hemi deposit in 2020, and Gold Fields paid $3.7 billion for Gold Road, which found the Gruyere deposit in 2013.
The big gold miners are flush with cash at the moment, and we don’t think their appetite for juniors making discoveries has dulled.
Liontown (ASX: LTR) Commits $389 Million to Kathleen Valley Lithium Expansion
Lithium major Liontown (ASX: LTR) signed off $389 million on Wednesday to make its WA mine half as big again, and on Thursday its holders sold the stock down 15%.
They sold because it’s a big bill and it won’t bear fruit until 2028, when the bigger mine starts producing.
Lithium carbonate is still about double its 2025 low, even after it fell 22% in September.
It’s Liontown’s second spend on lithium in a month. Four weeks ago we wrote about it buying into a salt flat in Argentina.
The WA mine is Kathleen Valley. It processes 2.8 million tonnes of ore a year and the expansion takes it to 4.2 million.
Spodumene concentrate is what Liontown ships to battery makers. It expects to produce 390,000 to 440,000 tonnes this financial year and about 780,000 tonnes a year from 2030.
A bigger mine is cheaper to run per tonne. Liontown expects each tonne to cost $840 to $920 to produce after the expansion, down from $1,050 to $1,250 this year.
It will pay for the build from the $561 million it had in the bank at June and from what the mine earns along the way.
What We’re Watching Next Week on the ASX
It was a bit of a quieter week on markets this week.
Daylight saving kicked in this morning, so a reminder the ASX opens an hour earlier for anyone in a state without it from tomorrow. We’ll be up for it, because a few companies in our portfolio are drilling or waiting on the lab.
September quarterlies start landing this month too, which show how much money each junior has left.
China is also back from its National Day holiday on Thursday. Copper hit a record last month but just had its worst week since April while its biggest buyer was away.
We’re bullish copper and want to see if China’s factories keep buying at about US$14,250 a tonne.
And on Tuesday the fundies start the bidding for Firmus, the biggest float in Australia since Telstra and probably the most talked about since Guzman y Gomez. A fair bit to watch in the weeks ahead.
Till next week.
General advice, disclosure and confidentiality
General advice warning
The contents of this document are intended to provide general securities advice only and have been prepared without taking account of your objectives, financial situation or needs. Because of that you should, before taking any action to acquire or deal in, or follow a recommendation (if any) in respect of any of the financial products or information mentioned in this document, consult your own investment advisor to consider whether that is appropriate having regard to your own objectives, financial situation and needs. If applicable, you should obtain the Product Disclosure Statement relating to the relevant financial product mentioned in this document (which contains full details of the terms and conditions of the relevant financial product) and consider it before making any decision about whether to acquire the financial product. Whilst Equities Club Pty Ltd (”Equities Club”) believes information contained in this document is based on information which is believed to be reliable, its accuracy and completeness are not guaranteed and no warranty of accuracy or reliability is given or implied and no responsibility for any loss or damage arising in any way for any representation, act or omission is accepted by Equities Club or any officer, agent or employee of Equities Club or any related company.
Neither Equities Club, nor any of its directors, authorised representatives, employees, or agents, makes any representation or warranty as to the reliability, accuracy, or completeness, of this document or any advice. Nor do they accept any liability or responsibility arising in any way (including negligence) for errors in, or omissions from, this document or advice.
Disclosure
The directors, authorised representatives, employees and associated persons of Equities Club may have an interest in the financial products discussed in this document and they may earn brokerage, commissions, fees and advantages, pecuniary or otherwise, in connection with the making of a recommendation or dealing by a client in such financial products. Equities Club owns 500,000 KTK shares, 200,000 10X shares, and 4,500,000 EVG shares at the time of publishing this article. Equities Club has been engaged by KTK, 10X and EVG at the time of writing.
Confidentiality notice
The information contained in and accompanying this communication is strictly confidential and intended solely for the use of the intended recipient/s. The copyright in this communication belongs to Equities Club. If you are not the intended recipient of this communication please delete and destroy all copies immediately.
Equities Club Ltd (CAR No. 001308139) is a corporate authorised representative of ShareX Pty Ltd, Australian Financial Services Licence (AFSL) No 519872.